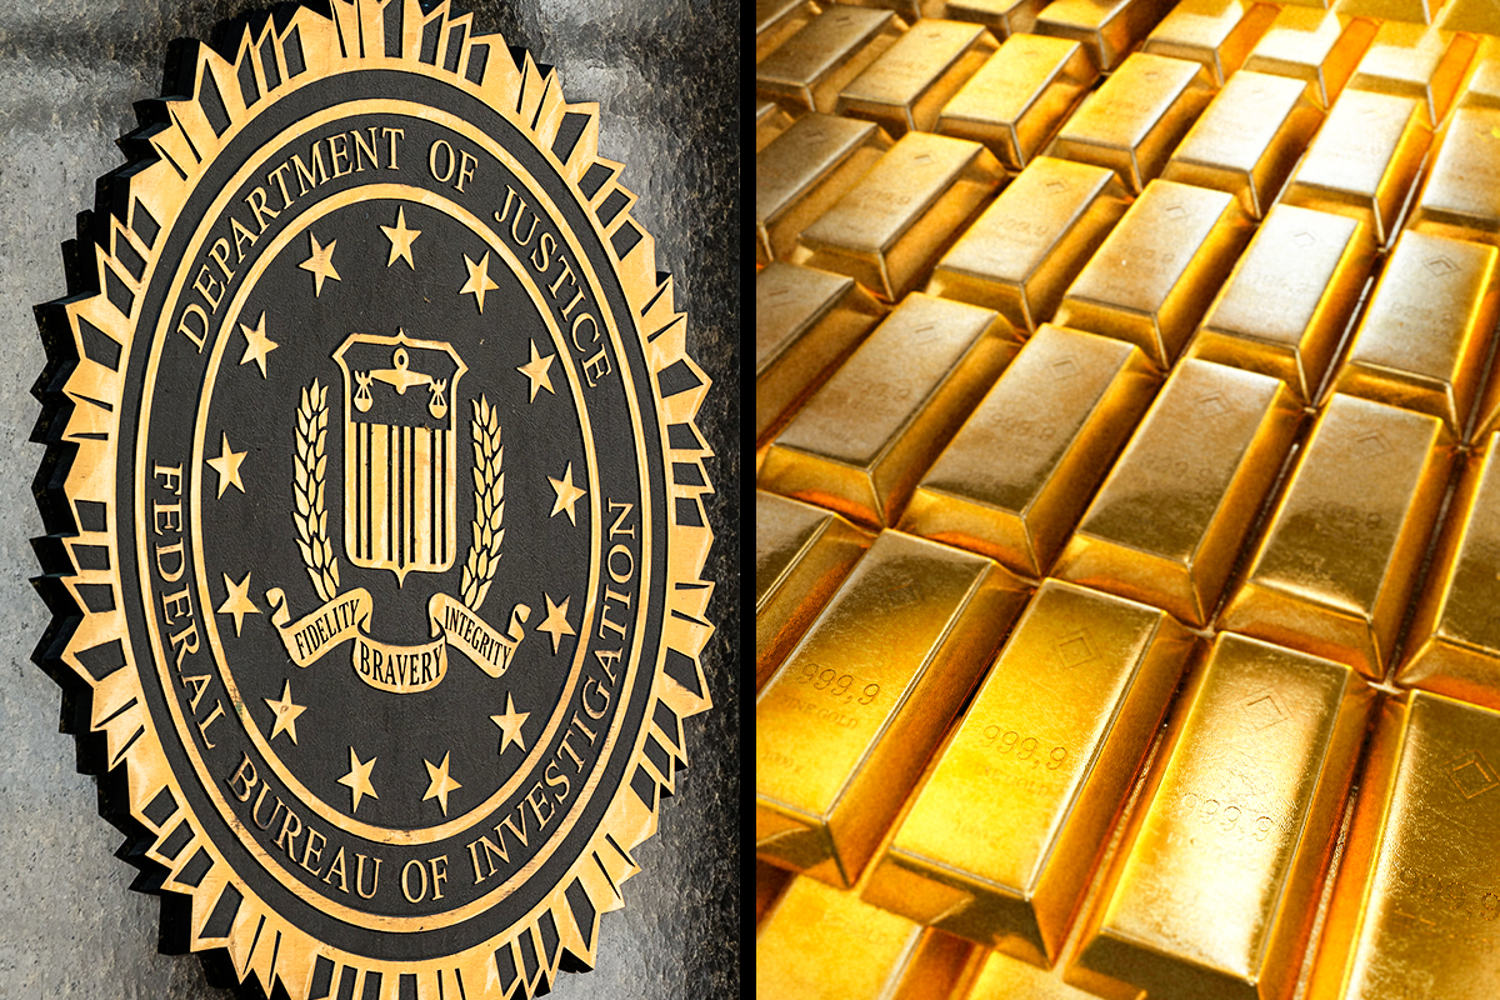
The detection of structural vulnerabilities inside federal intelligence accounting mechanisms requires examining how bureaucratic complexity creates systemic blind spots. When former CIA officer David J. Rush executed a multi-year scheme that defrauded the federal government of approximately $194 million—culminating in the accumulation of hundreds of gold bars, luxury vehicles, and extensive South Florida real estate—the failure extended far beyond individual malfeasance. It exposed the structural limits of oversight within highly classified operational funding environments.
The Anatomy of Institutional Capture
The mechanics of the operation relied on exploiting the opacity inherent in classified program budgets. Federal oversight traditionally functions on segregated duties, wherein internal audits, security clearances, and financial comptrollers operate across distinct verification layers.
The three primary vectors of vulnerability within this specific case include:
- Credential Authentication Failure: The initial vector involved falsified academic credentials and fabricated military service records that enabled entry and retention within the agency for nearly two decades. In high-clearance environments, reliance on institutional trust often creates a cognitive bias that lowers the friction of initial background verification.
- Compartmentalized Budget Isolation: Funds designated for specialized or classified initiatives are frequently shielded from standard inter-agency auditing to protect operational security. This isolation creates a structural blind spot, preventing routine financial reconciliation controls from flagging anomalous capital expenditures.
- Asset Diversion Channels: The conversion of liquid capital into physical bullion (nearly 300 gold bars) and high-value real estate represents a deliberate strategy to bypass traditional banking surveillance loops that normally trigger Suspicious Activity Reports (SARs) for large domestic currency transfers.
The Cost Function of Bureaucratic Secrecy
The operational friction between public accountability and national security classification creates a distinct risk profile. When an agency prioritizes the containment of classified disclosures, its internal response mechanism often favors swift, contained resolutions over exhaustive public transparency.
The cost function is defined by two competing variables: the institutional cost of public scandal versus the financial cost of unchecked internal fraud. In environments where programs operate under strict nondisclosure frameworks, the threshold required to trigger external financial audits is exceptionally high. This dynamic inadvertently incentivizes internal bad actors to target shielded budget lines, calculating that the institutional aversion to exposing classified workflows provides a protective buffer.
Systemic Remediation and Control Vectors
Preventing systemic recurrence necessitates redesigning the verification architecture of intelligence funding. Standard compliance models fail when applied to clandestine operations because they assume a transparent ledger.
Effective reform demands the introduction of zero-trust financial architecture within classified environments. This involves implementing automated cryptographic auditing for project-level fund allocation without compromising the operational security of the underlying intelligence mission. By decoupling the verification of expenditures from the operational clearance level of the individual managing them, agencies can re-establish internal controls that withstand individual executive overreach.
The resolution of the case through a pre-indictment plea framework underscores the immediate institutional priority: mitigating further exposure of administrative vulnerabilities. However, the structural lessons remain. Until internal accounting controls in classified sectors match the rigor of commercial forensic auditing, the structural incentive for internal resource diversion will persist.