Real estate markets frequently exhibit pricing anomalies where a property commands an acquisition cost drastically higher than its initial listing valuation. When an asset listed at eight million dollars clears the market at fifteen million dollars, standard explanations relying on generic market heat fail to capture the underlying financial mechanics. This divergence points to structural mispricing, asymmetric information distribution, and aggressive capital deployment by high-net-worth buyers who evaluate assets through alternative risk-adjusted return frameworks.
Evaluating this phenomenon requires deconstructing the transaction into three primary variables: the initial undervaluation by the listing entity, the scarcity premium of physical architectural assets that cannot be replicated, and the competitive friction introduced by sealed-bid or high-stakes auction dynamics.
The Mechanics of Initial Mispricing
The baseline error in a standard real estate valuation often stems from relying on historical comparable sales rather than replacement cost or utility-based pricing. A property aged over a century possesses specific non-linear attributes. Standard valuation models treat age as a depreciation factor, factoring in the systemic cost of deferred maintenance, outdated plumbing infrastructure, and archaic electrical distributions.
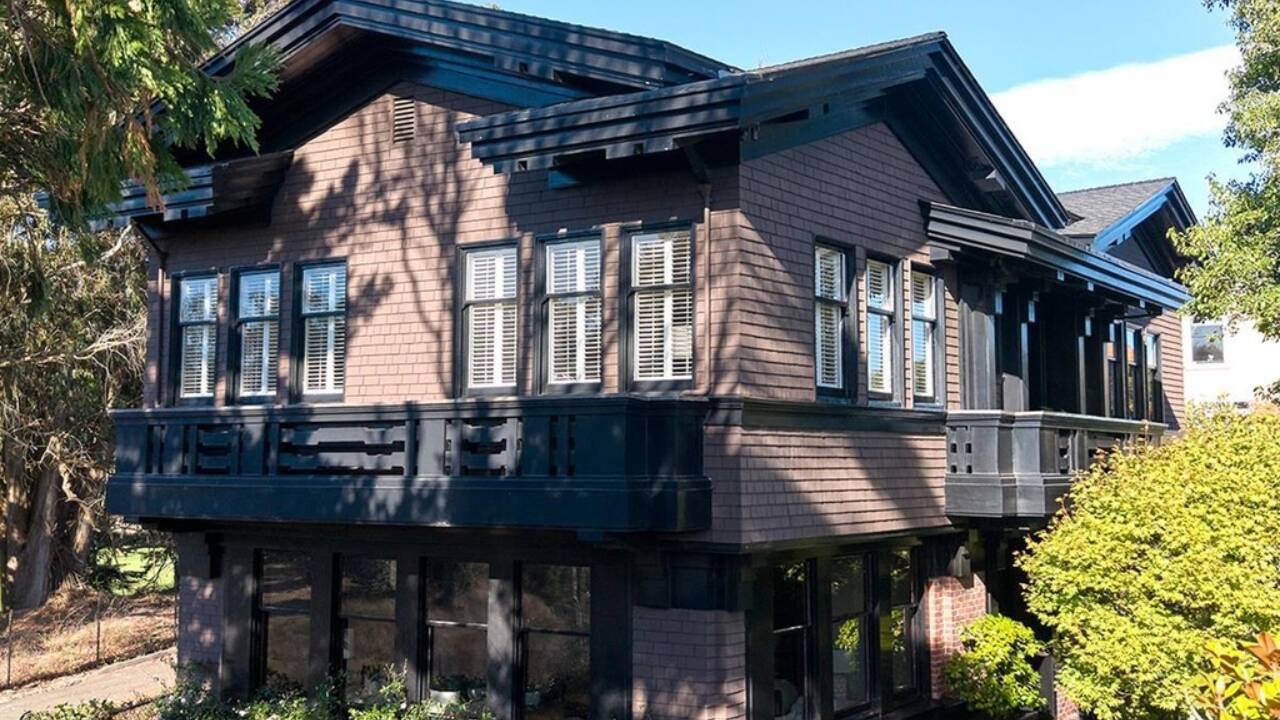
However, for ultra-prime real estate, age transitions from a liability to an irreproducible asset class. The craftsmanship, old-growth timber, localized stonework, and zoning grandfathering associated with a 112-year-old structure represent a sunk cost that modern construction economics cannot duplicate. When an asset is listed at eight million dollars, the pricing strategy typically reflects a lagging indicator approach—extrapolating from nearby transactions that lack identical structural provenance.
Sellers or their brokers may intentionally underprice an asset to stimulate artificial liquidity, lower days-on-market metrics, and ignite competitive bidding pools. This strategy shifts the burden of price discovery onto the market. In an efficient market, competing buyers quickly correct the mispricing. In an inefficient ultra-luxury market, aggressive underpricing acts as a catalyst that forces prospective buyers to bypass rational valuation bands to secure a scarce positional good.
Scarcity Economics and Positional Goods
Properties at this tier function less as functional shelter and more as positional goods. A positional good derives its value entirely from its limited supply and the relative status it confers upon the owner. Land constraints in established historical districts create a hard cap on supply. No amount of capital injection can manufacture an identical physical location or a century of provenance.
Buyers operating in this asset class evaluate the purchase through a wealth-preservation and capital-concentration lens rather than a traditional capitalization rate. For a buyer managing generational capital, spending fifteen million dollars on an asset perceived through a traditional eight-million-dollar lens does not represent a seven-million-dollar loss; it represents the clearing price required to internalize a finite, non-fungible monopoly asset.
The opportunity cost of losing the asset to a competitor often outweighs the financial delta between the list price and the clearing price. Consequently, the demand curve for ultra-prime real estate becomes highly inelastic within specific wealth brackets. Standard elasticity models break down because the utility gained from acquiring a unique trophy asset increases as the pool of available alternatives shrinks.
Asymmetry of Information and Transaction Friction
The mechanics driving a near-doubling of a property's price during a transaction cycle also expose structural inefficiencies in real estate data transparency. Public records and automated valuation models lack the granular data necessary to price bespoke historical assets accurately.
When multiple sophisticated buyers simultaneously recognize latent value—such as unexploited zoning rights, subterranean expansion potential, or historical tax credits—a bidding war ensues. Each bidder calculates their maximum willingness to pay based on private information or proprietary architectural assessments.
The transition from an eight-million-dollar valuation to a fifteen-million-dollar execution highlights the failure of traditional appraisal systems to price optionality. If a property sits on land with development or subdivision rights, or if the structural shell allows for a high-end modernization that preserves historical tax advantages, the acquisition cost must account for the net present value of those future cash flows or utility upgrades. Traditional list prices frequently ignore these embedded options, leaving a massive valuation gap that is only bridged when aggressive capital steps in to exercise them.
Capital Deployment Strategy for Asymmetric Assets
Navigating transactions characterized by extreme valuation variances requires a shift in analytical posture. Market participants who rely strictly on trailing historical comps will consistently miss opportunities or get priced out of structural shifts.
To evaluate similar assets effectively, acquisitions teams and private investors must isolate physical replacement cost, quantify the scarcity premium of historical zoning, and model the behavioral economics of competing bidders in closed-envelope environments. The fifteen-million-dollar clearing price is not an anomaly of irrational exuberance; it is the natural mathematical result of a finite asset meeting unconstrained capital in an inefficient market.