Read any mainstream energy report this week and you will get the exact same breathless, lazy narrative.
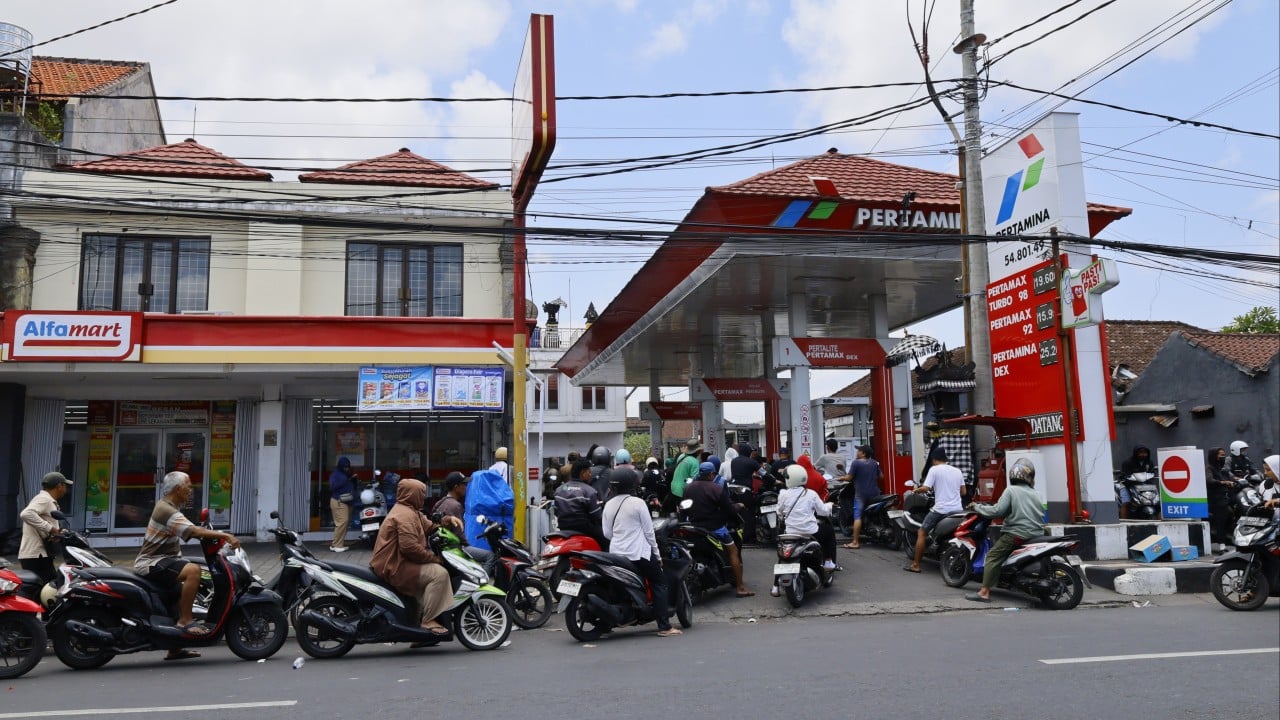
Wildfires are burning across Borneo and Sumatra. Haze is drifting across the Malacca Strait. Simultaneously, Jakarta is throttling piped natural gas exports to Singapore. The media loves a tidy villain, so they stitched these two unrelated events together into a dramatic tale of environmental retaliation and regional energy panic.
It makes for a great headline. It is also completely detached from how Southeast Asian energy markets, peatland ecology, and grid physics actually work.
If you are an energy trader, a regional policy analyst, or an executive running power-hungry data centers in Jurong, buying into the "haze-for-gas" panic will cost you money. The mainstream press is staring at the smoke while missing the real fire happening inside the balance sheets of Pertamina, Perusahaan Gas Negara (PGN), and Singapore’s Energy Market Authority (EMA).
The Lazy Consensus of Environmental Retaliation
Let us look at the dominant narrative first. Every time the Pollutant Standards Index (PSI) ticks upward in Singapore, commentators dust off the Transboundary Haze Pollution Act of 2014 and look toward Jakarta for signs of diplomatic friction. When news breaks that piped gas flows from South Sumatra or West Natuna are dipping, the pundits immediately assume one of two things: either Jakarta is punishing Singapore for criticizing its forestry management, or the fires themselves are physically choking off gas infrastructure.
Both theories collapse under five minutes of basic scrutiny.
First, gas pipelines do not stop working because the air is smoky. The bulk of Singapore’s piped Indonesian gas comes from the Grissik-Singapore pipeline originating in South Sumatra and the West Natuna Transportation System (WNTS) sitting offshore in the South China Sea. Subsea pipes and buried high-pressure transmission lines are immune to surface-level peat smoke. Unless a fire literally melts a compressor station—which has not happened—the haze has zero physical impact on molecular flow rates.
Second, Jakarta does not use sovereign gas contracts as petty diplomatic leverage over haze complaints. Indonesia’s upstream oil and gas regulator, SKK Migas, operates on cold, hard fiscal math. When Indonesia cuts gas exports to Singapore, it is not throwing a diplomatic tantrum. It is scrambling to cover a massive domestic supply deficit caused by years of upstream underinvestment, maturing gas fields, and a politically mandated Domestic Market Obligation (DMO).
I have watched regional energy desks lose millions of dollars mispricing Southeast Asian LNG spreads because they traded on geopolitical headlines instead of reading SKK Migas production reports. When you confuse structural field decline with temporary diplomatic friction, you bet on a quick resolution that never arrives.
Why Jakarta Is Actually Turning Down the Tap
To understand why Indonesian gas flows are shrinking, stop looking at satellite maps of Borneo hotspots and start looking at reservoir pressure in the Corridor Block.
For over two decades, Singapore relied on cheap, long-term piped natural gas from Indonesia and Malaysia to generate roughly 95% of its electricity. Those contracts were signed in an era when Indonesia was awash in stranded gas and desperate for foreign currency.
That era is dead.
Indonesia’s domestic industrial demand—driven by state-mandated downstreaming policies, nickel smelters, fertilizer plants, and state utility PLN—has exploded. At the same time, legacy fields in South Sumatra are hitting natural decline curves. You cannot legislate reservoir pressure back into existence. When the gas coming out of the ground drops, Jakarta faces a binary choice: honor export contracts to a wealthy neighbor, or keep its own domestic factories running and prevent blackouts in Java and Sumatra.
Every government on earth makes the exact same choice. Domestic political survival always beats export commitments.
When Jakarta announced that it would not renew certain piped gas contracts after 2023 and subsequently scaled back volumes, it was executing a multi-year pivot toward domestic energy security. The timing of recent flow reductions overlapping with the dry season in Kalimantan and Sumatra is pure seasonal coincidence. Dry weather triggers peat fires. Dry weather also spikes cooling demand and lowers hydroelectric output across Indonesia, forcing PLN to burn more gas domestically.
The fires and the gas cuts share a common trigger—the dry monsoon—not a causal relationship.
Singapore Built a Fortress While Everyone Was Watching the Smoke
Here is the second half of the story that the panic-merchants completely ignore: Singapore saw this coming ten years ago and quietly neutralized the threat.
If Indonesia had slashed piped gas deliveries in 2010, Singapore would have plunged into rolling blackouts within forty-eight hours. The city-state had no liquefied natural gas (LNG) import terminals, negligible grid-scale battery storage, and zero cross-border power interconnectors capable of carrying utility-scale baseload.
Today, the Singaporean grid is an entirely different beast.
Following the 2021 global energy crisis—when piped gas disruptions from West Natuna collided with tight global LNG markets and blew up several independent electricity retailers—the Energy Market Authority (EMA) stopped treating energy security as a market efficiency exercise and started treating it like national defense.
Consider the structural armor Singapore has bolted onto its power sector:
- The SLNG Terminal on Jurong Island: With four massive storage tanks and a throughput capacity exceeding 11 million tonnes per annum, Singapore can absorb spot and term LNG cargoes from Qatar, Australia, the United States, and Mozambique at will.
- The Standby LNG Facility (SLF): EMA literally maintains a state-backed reserve of LNG specifically designed to be injected into the grid the exact second piped gas from Indonesia or Malaysia dips below contracted nominations.
- Centralized Gas Procurement: Through Gasco, Singapore consolidated gas buying to secure long-term LNG supply deals rather than leaving vulnerable generation companies (gencos) exposed to volatile spot markets.
- Mandatory Fuel Reserves: Power generation companies are legally required to hold minimum stockpiles of diesel and distillate fuels, allowing combined-cycle gas turbines (CCGTs) to switch liquid fuels seamlessly if gas pressure drops.
Let us run a quick thought experiment to see how this plays out in reality. Imagine a scenario tomorrow morning where PGN cuts piped gas flow through the Grissik pipeline by 40% due to a sudden domestic shortfall in Sumatra. The press will scream about an energy crisis. Meanwhile, inside the EMA control room in Singapore, automated telemetry detects the pressure drop, triggers drawdowns from the Standby LNG Facility, spins up secondary fuel reserves if needed, and keeps the voltage across every semiconductor fab in Woodlands steady at 230 volts.
Consumers do not even see their lights flicker.
Dismantling the Wrong Questions
When mainstream outlets cover this story, they inevitably pivot to a set of predictable, flawed questions. If you want to actually understand the Southeast Asian energy market, you need to dismantle the premises behind them.
Is Singapore running out of power because of Indonesia?
No. Singapore is not running out of molecules; it is transitioning from cheap piped molecules to expensive seaborne molecules. The threat to Singapore is not physical scarcity—it is cost competitiveness. Piped gas from Sumatra was historically indexed to oil at rock-bottom slopes, giving Singaporean industry ultra-competitive power prices. Replacing that piped gas with global LNG exposes Singapore to the Japan-Korea Marker (JKM) and Henry Hub pricing dynamics. The real story is margin compression for Singaporean manufacturers, not empty gas tanks.
Can Singapore force Indonesia to honor the gas contracts?
Legally, commercial gas sales agreements (GSAs) contain strict take-or-pay and deliver-or-pay clauses, backed by international arbitration mechanisms in Singapore or London. Practically, you cannot force a sovereign nation to export molecules it needs to keep its own lights on. Invoking force majeure or paying modest liquidated damages is vastly cheaper for an Indonesian state enterprise than triggering domestic industrial unrest. Singapore’s policymakers know this, which is why they spend their political capital building subsea power cables to Australia, Cambodia, and—ironically—Indonesia’s own Riau Islands for solar imports, rather than fighting losing legal battles over dying gas fields.
Does the haze actually affect Singapore’s energy transition?
Yes, but in the exact opposite way people assume. The narrative usually claims haze makes Singapore angry at Indonesia, stalling regional cooperation. In reality, severe transboundary haze forces Jakarta and Singapore into deeper, more pragmatic alignment on land management and green capital. Singaporean banks and green finance funds hold the capital Indonesia desperately needs to retire coal plants under the Just Energy Transition Partnership (JETP) and restore degraded peatlands. Haze does not break the relationship; it reminds both capitals that they share a single ecological and economic airshed.
The Uncomfortable Truth About the "Green" Pivot
Before we crown Singapore as an untouchable energy mastermind, honesty requires admitting the massive vulnerability baked into its current strategy.
By pivoting away from Indonesian piped gas toward global LNG and cross-border renewable imports, Singapore has traded regional concentration risk for global maritime choke-point risk and carbon intensity.
LNG is not clean. When you factor in the energy required to supercool natural gas to minus 162 degrees Celsius in Qatar or Texas, ship it thousands of miles on boil-off-burning tankers through the Strait of Hormuz and the Malacca Strait, and regasify it on Jurong Island, the lifecycle fugitive methane and carbon emissions skyrocket compared to a short, pressurized pipe running from Sumatra.
Furthermore, Singapore’s ambitious plan to import 4 gigawatts of low-carbon electricity by 2035 relies heavily on subsea high-voltage direct current (HVDC) cables running straight through Indonesian territorial waters. Whether the electrons come from solar farms in Bulan Island, hydro dams in Sarawak, or massive solar arrays in northern Australia via SunCable, Jakarta holds the geographic keys to the seabed.
If Singapore alienates Jakarta over bilateral gas disputes or heavy-handed diplomatic lecturing during haze season, the blowback will not be a cut in dying natural gas pipelines. The blowback will be a quiet, bureaucratic delay in seabed survey permits for the subsea power cables that Singapore’s 2040 net-zero roadmap depends on.
What You Should Actually Be Watching
Stop refreshing air quality index maps to predict Southeast Asian energy flows. If you want real signal instead of media noise, track these three metrics instead:
- SKK Migas Lifting Reports: Watch the quarterly gas lifting numbers from the Corridor Block and Natuna Sea. The gap between contracted export volumes and actual reservoir output tells you the exact pace at which Singapore must sign new long-term LNG off-take agreements.
- JKM-Brent Spreads: Because Singapore’s legacy piped gas was oil-indexed while its replacement supply leans heavily on LNG, the spread between Asian spot LNG (JKM) and Brent crude dictates the electricity tariff spikes hitting Singaporean commercial and industrial consumers.
- Subsea Cable Permitting in the Riau Archipelago: Ignore diplomatic rhetoric around haze. Watch whether Indonesia’s Ministry of Energy and Mineral Resources (ESDM) continues granting export licenses for solar-generated electricity from Batam and Bintan into Singapore. That is the true barometer of bilateral energy trust.
The media wants you to believe that smoke on the horizon means an energy crisis in the Straits. They are wrong. The gas cuts are the inevitable death rattle of an old fossil fuel architecture that both countries have already moved past.
The real game is no longer about who controls the gas pipes under the sea—it is about who controls the copper cables that will replace them.