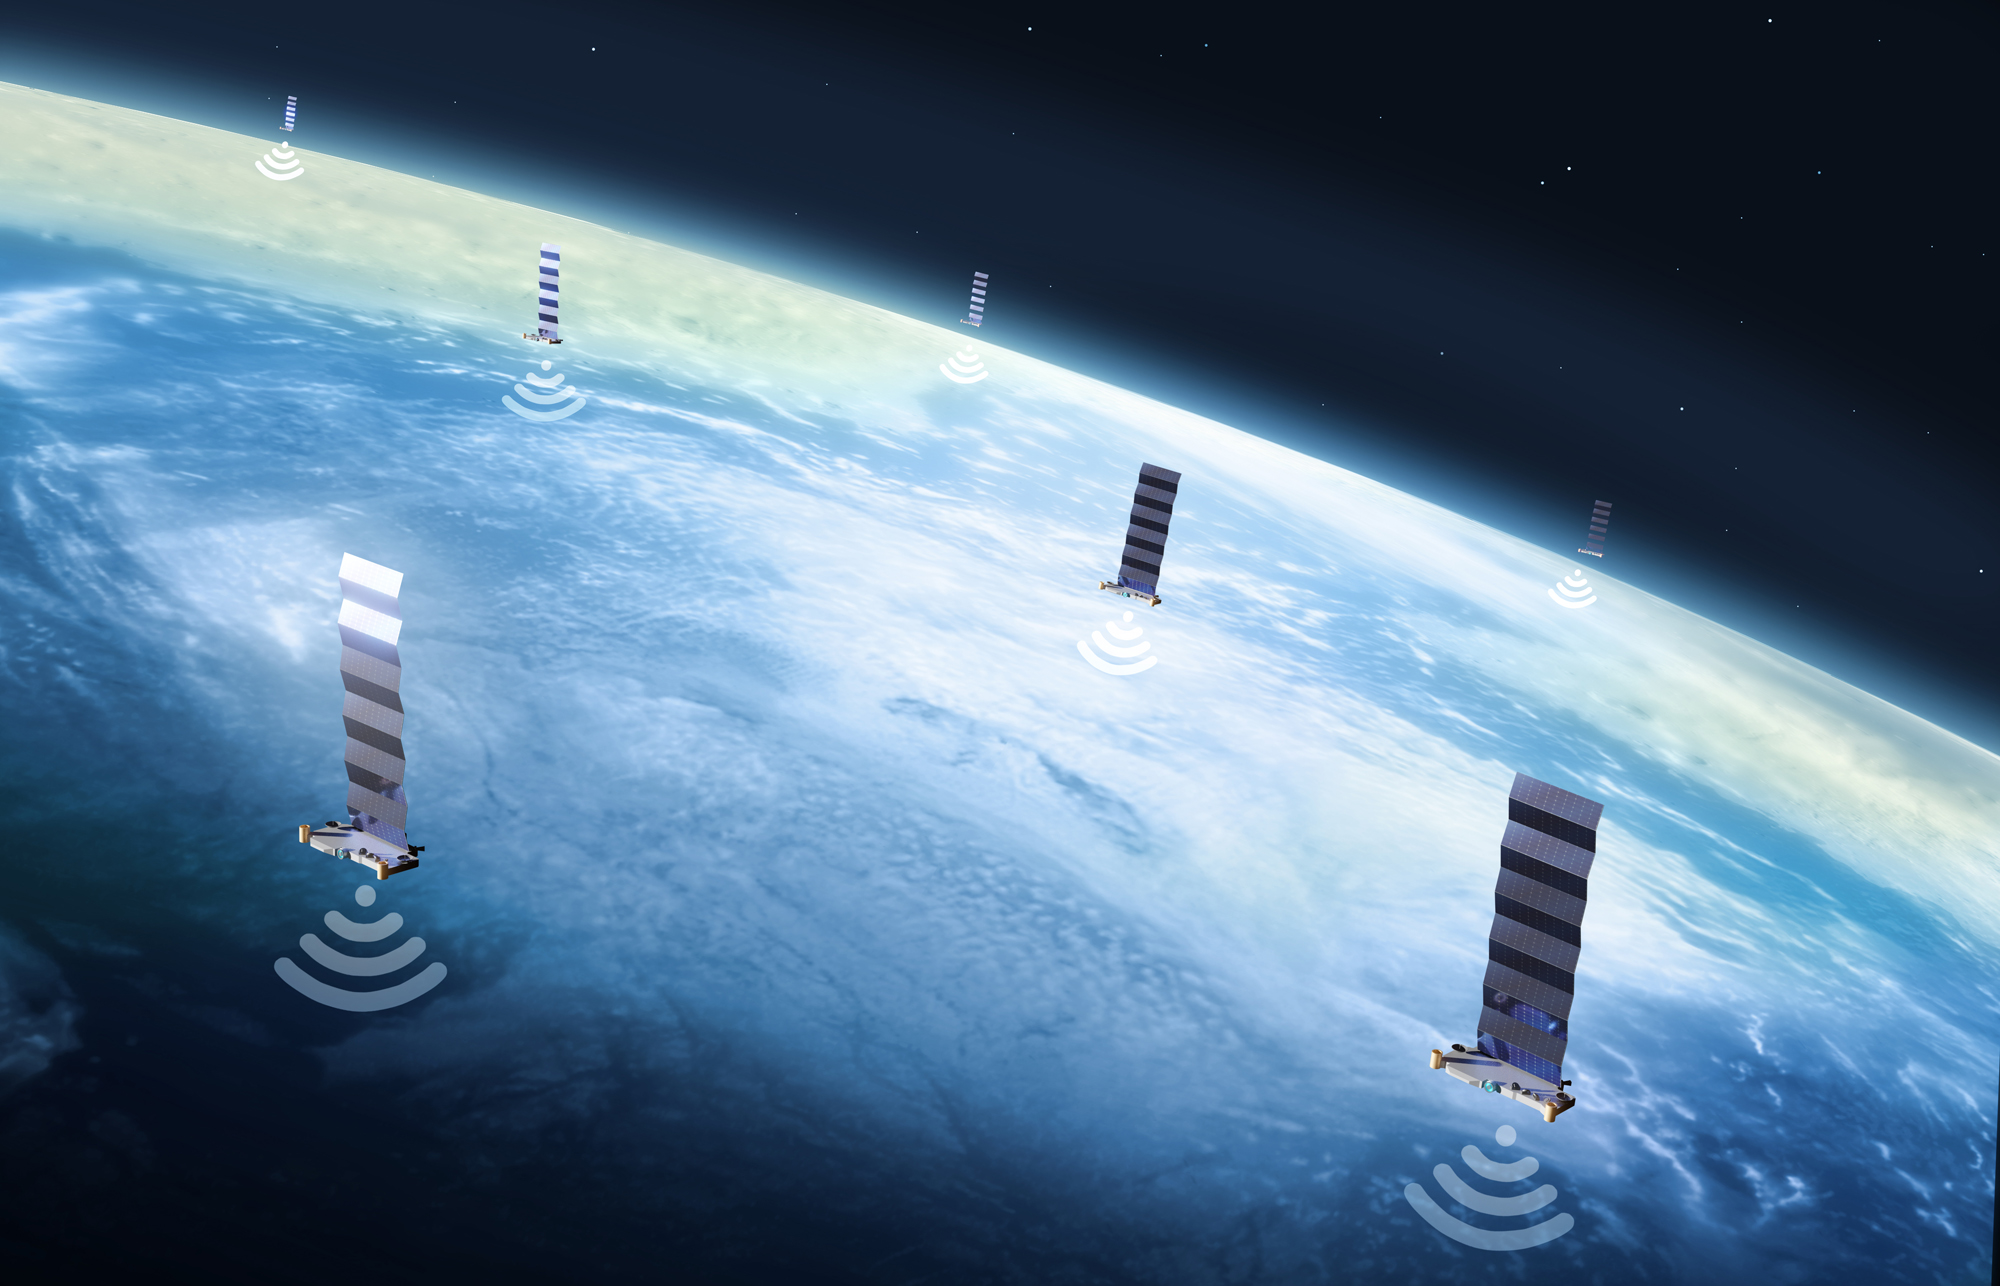
Acquiring wireless spectrum does not build a nationwide mobile network; it buys the legal right to radiate radio energy into contested airwaves while transferring tens of billions of dollars in capital expenditure, regulatory scrutiny, and engineering integration onto SpaceX's balance sheet. Coverage around SpaceX's push into direct-to-mobile connectivity—including its October 2026 agreement to acquire nationwide low-band 800 MHz spectrum licenses from Grain Management (reportedly around $8 billion) alongside earlier spectrum transactions with EchoStar and T-Mobile—often frames the story as Elon Musk adding yet another task to an already crowded schedule. That framing misses the real mechanics. Spectrum is raw material, not finished infrastructure, and every megahertz acquired on paper shifts SpaceX's operational load across orbital hardware, terrestrial cell sites, carrier relationships, and Federal Communications Commission (FCC) approvals.
To evaluate what these spectrum moves actually mean for SpaceX and its leadership, this analysis separates known facts from educated hypotheses, maps the three operational burdens created by spectrum accumulation, traces the second-order bottlenecks that simpler commentary overlooks, and lays out a disciplined execution sequence for turning spectrum licenses into working mobile service. For a closer look into this area, we suggest: this related article.
Known Facts Versus Educated Hypotheses
Clear separation between verified facts and analytical hypotheses is essential when evaluating a high-speed telecom expansion where technical claims and commercial negotiations are still evolving.
Known facts established by public reporting and filings: For further background on the matter, extensive analysis is available on MarketWatch.
- SpaceX agreed in October 2026 to acquire a nationwide portfolio of up to 14 MHz of paired low-band spectrum in the 800 MHz range from Grain Management, subject to FCC approval, with Reuters reporting an estimated deal value near $8 billion.
- SpaceX has pursued major spectrum transactions beyond the Grain Management agreement, including a major 2025 EchoStar spectrum deal and subsequent follow-on and 800 MHz arrangements.
- Low-band frequencies around 800 MHz propagate farther and penetrate buildings better than higher-frequency bands, which makes them useful for rural reach and indoor signals.
- SpaceX's existing direct-to-cell offerings have relied heavily on partnerships with terrestrial mobile operators—such as T-Mobile's T-Satellite service launched with SpaceX in July 2025—while incumbent carriers including AT&T, T-Mobile, and Verizon have also pursued their own satellite connectivity initiatives and partnerships (such as backing AST SpaceMobile or forming joint satellite efforts).
- SpaceX has announced ambitions for next-generation direct-to-cell capabilities—including large satellite constellations and substantially higher per-satellite bandwidth claims—while still needing terrestrial coordination and infrastructure to build a full mobile footprint.
Educated hypotheses based on telecom economics and physics:
- Buying nationwide 800 MHz and 2 GHz-class spectrum lowers SpaceX's long-term dependence on carrier-supplied spectrum for direct-to-device service, yet it simultaneously increases SpaceX's exposure to terrestrial tower leasing, backhaul costs, and dense-urban capacity limits.
- Even if next-generation satellites deliver dramatically higher capacity than first-generation direct-to-cell spacecraft, shared radio spectrum faces hard Shannon-capacity and interference ceilings in high-density metro areas unless paired with dense terrestrial sites or local hardware.
- Moving from a wholesale satellite partner to a standalone or semi-independent mobile contender alters SpaceX's commercial dynamics with incumbents that currently co-market or support direct-to-cell access.
The Three Burdens of Spectrum Accumulation
A surface reading of "piling onto Musk's plate" treats executive attention as a single bucket. In practice, acquiring spectrum creates three distinct operational burdens that require different teams, timelines, and risk tolerances.
1. Capital Allocation and Balance Sheet Load
Spectrum purchases are upfront capital commitments whose cash returns depend on multi-year deployment and regulatory sign-off. Even when headline figures are reported or estimated in the billions, the purchase price is only the entry ticket. Turning licensed frequencies into commercial service requires base station radios, antenna systems, network core software, backhaul links, and ongoing satellite replenishment.
Unlike rocket launches or broadband terminals where SpaceX controls much of the vertical stack, terrestrial wireless buildouts expose the company to familiar telecom capital intensity: site acquisition, power connections, fiber transport, and local permitting. If regulatory review drags on or hardware rollouts slip, capital sits tied up in non-revenue-generating assets.
2. Radio Physics and Link-Budget Complexity
Low-band spectrum around 800 MHz helps overcome path loss and wall attenuation compared to higher bands, yet low-band channels are narrow—14 MHz of paired spectrum is a modest slice of bandwidth when shared across millions of active handsets. Physics enforces a trade-off between coverage area and throughput density.
A satellite beam covering hundreds of kilometers shares limited spectrum across every user inside that footprint. Pushing reliable signals indoors to unmodified smartphones from low Earth orbit also demands high antenna gain and careful power-flux-density compliance so satellite transmissions do not cause harmful interference to terrestrial or adjacent services. Adding spectrum gives SpaceX more frequencies to work with, but integrating satellite beams with terrestrial cells introduces handoff, timing, and interference engineering problems that do not exist in a single-tier network.
3. Regulatory and Commercial Friction
Spectrum transfers in the United States require FCC approval, during which competitors, public-interest groups, and incumbent carriers can raise interference, competition, or public-interest objections. A deal signed in October does not mean immediate commercial operation.
At the same time, spectrum ownership reshapes relationships with mobile network operators. Partners that welcome satellite coverage to fill dead zones may view a spectrum-holding satellite operator differently if that operator gains the ability to bypass carrier bottlenecks or compete more directly for subscribers and enterprise accounts. Managing both cooperation and rivalry at once adds commercial friction that cannot be solved simply by launching more rockets.
Cause-and-Effect Chains Simpler Coverage Misses
Articles built around executive overload usually stop at the headline ("Musk has too much to do"). Operational analysis looks at the causal chains connecting spectrum deals to real-world performance.
Why Spectrum Does Not Equal Instant Nationwide Mobile Service
- License transfer precedes network readiness: FCC approval authorizes ownership or transfer of rights, not instant subscriber traffic.
- Device ecosystems lag spectrum deals: A frequency band only helps end users if compatible modems, antennas, and band support exist in smartphones or auxiliary hardware—and if roaming or carrier agreements allow traffic to pass smoothly.
- Capacity bottlenecks move rather than disappear: Adding 800 MHz low-band spectrum improves reach and indoor penetration, but narrow low-band channels saturate quickly in dense cities. Without terrestrial densification or supplemental capacity tiers, congestion shifts from "no signal" to "slow or congested data."
How Satellite-Terrestrial Convergence Changes the Operating Model
Direct-to-device satellite connectivity started primarily as a coverage extension—filling gaps in remote areas, oceans, and disaster zones where cell towers are sparse or absent. Buying dedicated spectrum pushes the model toward integrated hybrid connectivity, where space and ground elements work together.
That shift changes every operational metric. Instead of optimizing solely for sky visibility and orbital pass schedules, network engineers must manage indoor penetration, urban multipath fading, handoffs between orbital and terrestrial cells, and consistent latency under heavy load. For leadership, the challenge is less about "too many projects" in the abstract and more about cross-domain integration—getting space systems, RF engineering, terrestrial site operations, and regulatory affairs to move on synchronized schedules.
What People Usually Ask About This Shift
- Does buying 800 MHz spectrum make Starlink a traditional mobile carrier? No, not by itself. Spectrum is a foundational input, but becoming a full-scale mobile carrier requires terrestrial infrastructure, billing and roaming systems, device support, customer acquisition, and regulatory clearance.
- Why pursue low-band spectrum if Starlink already has satellites in orbit? Low-band frequencies travel farther and penetrate walls better than higher frequencies, addressing coverage and indoor signal challenges that higher bands struggle with.
- Does more spectrum eliminate the need for carrier partnerships? Not in the near term. Even with acquired spectrum, existing handset ecosystems, incumbent tower footprints, and carrier distribution channels make partnerships—or phased hybrid models—practical during transition periods.
Operational Playbook for Turning Spectrum Into Service
When a company acquires scarce spectrum while scaling a complex satellite constellation, execution discipline matters more than announcements. A practical operating sequence follows four stages.
- Sequence regulatory filings ahead of capital commitments: Map FCC review milestones, public-comment windows, and potential interference conditions before locking in irreversible ground buildout schedules. Build contingency plans for delayed approvals or modified operating terms.
- Segment use cases by frequency physics: Assign low-band spectrum primarily to wide-area coverage, rural reach, and challenging indoor links where propagation advantage matters most, while reserving higher-capacity links and satellite capacity for bandwidth-heavy demand. Avoid promising urban fiber-like throughput solely on narrow low-band channels.
- Establish clear boundaries between standalone and partner modes: Define explicitly where SpaceX operates as an infrastructure or connectivity partner to mobile carriers versus where it builds direct customer or enterprise relationships. Ambiguity creates friction with partners whose networks still carry most mobile traffic.
- Gate scale-up on measured link and congestion telemetry: Tie large-scale commercial expansion to empirical field metrics—packet loss, handoff drop rates, indoor signal margin, and peak-hour cell/beam throughput—rather than theoretical bandwidth projections.
Strategic Limits and Trade-Offs
No spectrum portfolio or orbital architecture removes every constraint in wireless networking. Every strategic choice carries trade-offs that leadership must actively manage.
- Spectrum scarcity is physical, not merely financial: Even deep pockets cannot expand the laws of physics governing bandwidth per hertz or co-channel interference in crowded bands.
- Vertical integration raises fixed costs: Building more of the stack in-house increases control and speeds certain iterations, but it also raises fixed overhead and execution risk if market demand or timelines shift.
- Regulatory timelines are outside unilateral control: Unlike internal engineering sprints, agency reviews and legal challenges move on external calendars, creating schedule risk regardless of how fast rockets fly.
Strategic Recommendation
SpaceX should treat its spectrum acquisitions as a phased hybrid coverage play rather than an immediate replacement for terrestrial mobile networks—prioritizing FCC clearance, targeted low-band indoor/rural use cases, and strict capacity gating before scaling broad consumer mobile claims. By ring-fencing terrestrial buildout milestones behind regulatory and technical readiness gates, leadership can protect capital efficiency and keep space-system execution focused while testing where spectrum ownership delivers genuine commercial leverage.