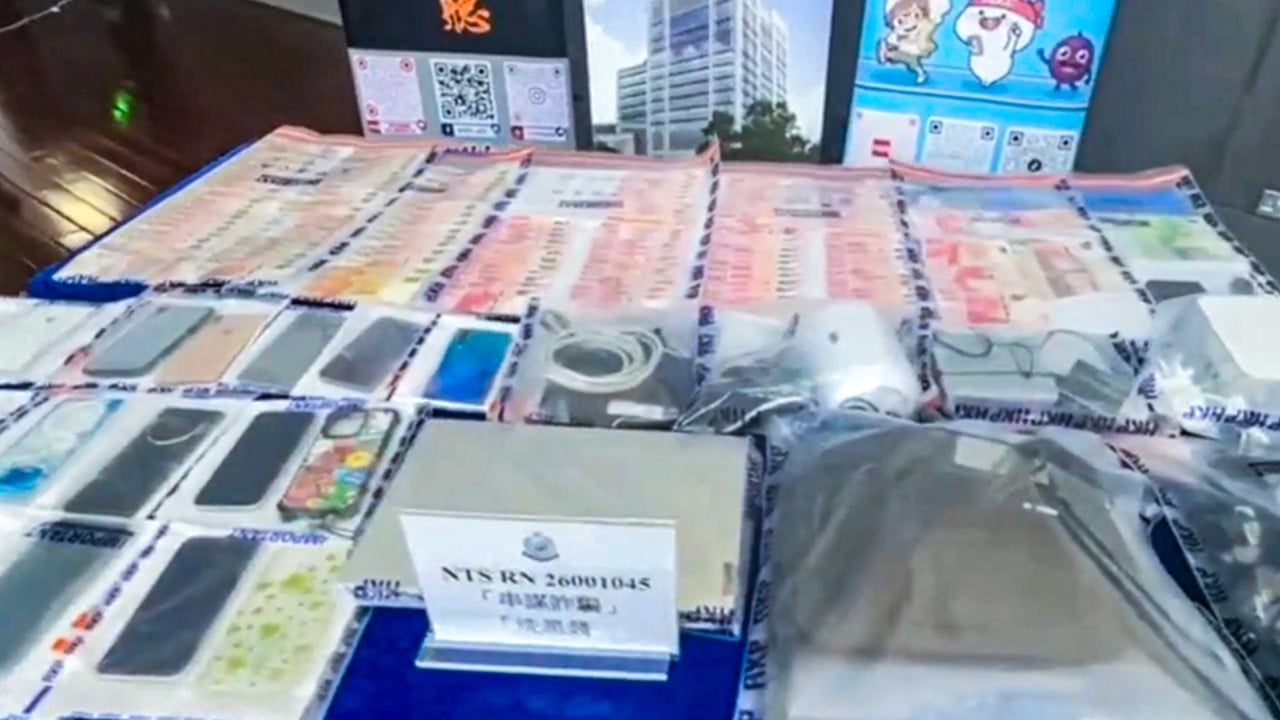
Modern financial crime has evolved from localized opportunism into structured corporate engineering. When law enforcement agencies dismantle networks such as the reported Hong Kong syndicate tied to HK$2.16 million in illicit proceeds, public commentary typically defaults to moral panic over youth deviance or technological alienation. This analytical failure obscures the underlying mechanics. The operational integration of students into criminal syndicates is not an anomaly of character; it is a predictable convergence of economic vulnerability, asymmetric risk distribution, and specialized labor demand within illicit markets.
To understand how student populations become structural nodes in fraud networks, one must deconstruct the internal economics of modern syndicates. Traditional organized crime relied on physical coercion and insular hierarchies. Contemporary cyber-enabled fraud, encompassing phishing infrastructure, deceptive recruitment funnels, and localized money laundering, operates on network-based modularity.
The Labor Economics of Syndicated Fraud
Fraud syndicates face a severe scaling constraint: velocity. Moving illicit capital from point of extraction to final obfuscation requires a high volume of transactional endpoints to avoid automated threshold triggers within traditional banking systems. Utilizing established criminal identities raises immediate flags; hence, syndicates require pristine profiles—individuals with unblemished credit histories, active demographic compliance, and access to domestic financial infrastructure.
University students represent an optimal labor pool for this specific operational bottleneck.
- Pristine Credit and Identity Profiles: Students possess clean statutory records, active bank accounts unencumbered by historical flaggings, and demographic characteristics that bypass baseline institutional suspicion.
- Liquidity Stress and Asymmetric Payoffs: Structural inflation, high urban living costs, and stagnant entry-level compensation create acute short-term cash flow pressures. A syndicate offering immediate liquidity for the simple act of "lending an account" or executing a transaction exploits this economic margin.
- Compartmentalized Risk Awareness: Pre-professional populations frequently miscalculate the legal velocity of financial facilitation, viewing administrative complicity as a regulatory infraction rather than a severe felony conspiracy.
The mechanics of recruitment rely heavily on institutional camouflage. By disguising operations behind legitimate-seeming administrative facades—such as fraudulent data-entry positions, remote marketing optimization, or promotional gig work—syndicates lower the cognitive friction of entry. Victims and complicit participants alike are funneled through algorithmic platforms where the true vector of value transfer is obscured.
The Transactional Cost Function of Laundering
A HK$2.16 million ledger cannot be moved through a single pipeline without inviting immediate regulatory intervention. The fundamental problem facing financial crime operators is the cost of friction. Every tier of transfer, conversion, and withdrawal incurs a decay coefficient through fees, currency conversion losses, and the risk of account freezing.
Syndicates mitigate this cost function by distributing the liability across multiple peripheral nodes. Students operating as core members or low-level facilitators function as distributed ledgers of exposure. If an account is flagged by anti-money laundering (AML) algorithms, the loss of that single endpoint represents a marginal operational write-off for the syndicate leadership, while the localized legal consequence falls entirely on the individual account holder.
The anatomy of this operation relies on three distinct operational phases:
- Acquisition of Endpoints: Securing secondary or primary bank credentials through coercion, deception, or direct financial purchase.
- Velocity Injection: Routing fragmented sums through localized peer-to-peer networks, virtual assets, or commercial fronts to decouple the funds from the primary fraud vector (such as romance scams or employment phishing).
- Consolidation and Extraction: Aggregating the cleaned fractions into sovereign liquidity pools accessible to syndicate controllers.
Regulatory Blind Spots and Institutional Friction
Traditional banking compliance relies heavily on static rule-based systems—velocity checks, geo-location anomalies, and unusual transaction thresholds. However, when transactional behavior mimics legitimate peer-to-peer commerce or standard student remittances, rule-based systems exhibit high rates of false negatives.
Furthermore, jurisdictional boundaries complicate institutional oversight. While financial institutions deploy advanced machine-learning models to detect anomalies, the speed at which syndicates adapt their obfuscation patterns—shifting from fiat layering to decentralized assets—outpaces traditional regulatory adjustment cycles. The utilization of human vectors who voluntarily or unwittingly bypass internal controls introduces a vulnerability that software alone cannot patch.
Strategic Forecast and Risk Mitigation
Mitigating this vector of financial crime requires moving beyond reactive enforcement and punitive deterrence. Because the economic incentives driving student participation remain high—driven by systemic cost-of-living pressures—deterrence via penal severity alone yields diminishing returns.
Financial institutions and academic institutions must alter the structural calculus of risk. This involves implementing real-time behavioral analytics that evaluate account usage anomalies specifically correlated with youth demographic profiles, alongside mandatory financial literacy frameworks that explicitly model the legal consequences of digital proxy laundering. Until the structural cost of recruitment outweighs the operational utility of pristine profiles, syndicates will continue to treat student populations as a renewable, low-cost liquidity infrastructure.